SEP IRA Rules for Business Owners With Variable Income
Learn how SEP IRA rules fit variable business income, employee obligations, cash flow, and building wealth outside an owner-dependent company. Card Description: A practical SEP IRA guide for business owners whose income changes from year to year.
Variable income changes retirement planning for a business owner. A strong year may create room for a meaningful contribution, while a slower year may make liquidity and operating reserves more important. A SEP IRA can fit that reality because employer contributions can generally vary from year to year.
The flexibility is useful, but it should not turn retirement saving into an afterthought. Owners still need a repeatable process for deciding how much cash stays in the business, how much moves to personal wealth, and what the company needs to become less dependent on the founder.
Chapter 3 of Walking to Destiny, “Every Hero Has a Flaw,” makes that last point especially important. If income falls whenever the owner steps away, the retirement plan and the business transition plan need to be discussed together.
A SEP IRA Is Flexible, but It Still Has Rules
A SEP is funded through employer contributions rather than employee salary deferrals. That can make it appealing to self-employed owners and businesses with uneven profits. The IRS provides SEP guidance covering eligibility, contribution calculations, and employee participation.
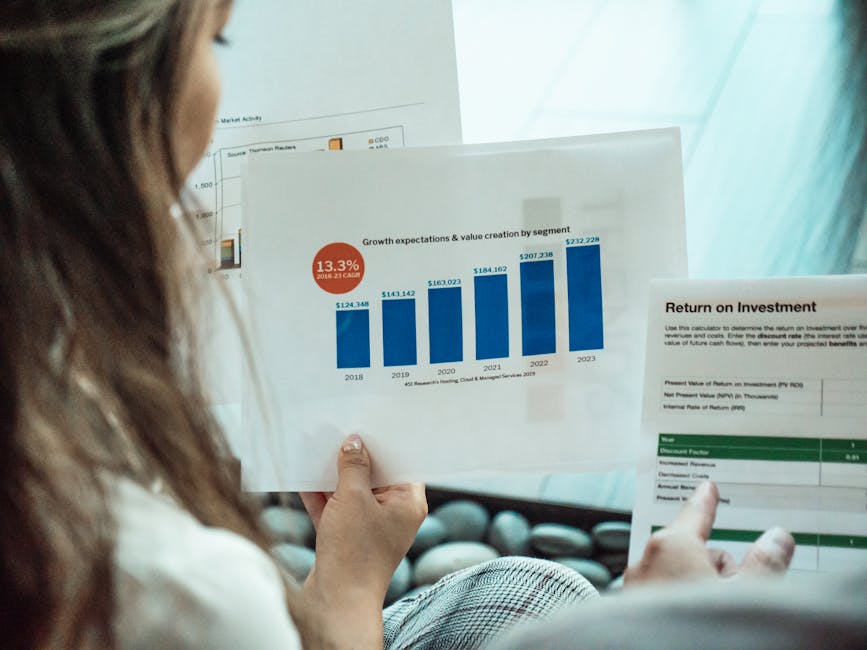
Financial planning workspace representing the balance between business liquidity and long-term retirement savings.
The word “flexible” should not be confused with “informal.” A business with eligible employees generally cannot treat the SEP as an owner-only account. Contribution decisions can create obligations for qualifying employees, so headcount and compensation need to be reviewed before the owner decides what the business can afford.
Use a Three-Bucket Cash-Flow Review
Divide available cash into three buckets. The first is operating liquidity: payroll, taxes, debt service, reserves, and near-term expenses. The second is business-building capital: hiring, systems, technology, and process improvements. The third is owner wealth: retirement accounts, personal reserves, and investments outside the company.
This framework prevents a profitable year from creating a contribution that leaves the company
financially tight. It also prevents every strong year from being reinvested into the business while the owner's personal balance sheet remains underdeveloped.
Apply the 30-Day-Away Test to Variable Income
Imagine the owner disappears for 30 days. Does revenue continue? Can employees make decisions? Do clients know who to call? Can the business keep sales and collections moving?
If income is variable because the owner personally drives most new business, the issue is larger than retirement-plan selection. The company may need stronger sales systems, delegated authority, or leadership depth. A SEP IRA can help move wealth outside the company, but the business also needs to become capable of producing value without constant founder involvement.
Do Not Let a Strong Year Create a Weak Balance Sheet
A large tax deduction can be attractive after an unusually profitable year. The owner should still ask what happens if the following year is slower. Before making a large contribution, review expected taxes, upcoming hires, equipment or technology needs, debt payments, and the size of the company's reserve.
This is especially important for owners approaching an exit. A buyer may care about management depth, recurring revenue, customer concentration, and operating consistency. Starving the business of resources needed to improve those areas can work against the transition goal.
When Employees Enter the Picture
A SEP can become more expensive when the business has eligible employees because the employer may need to contribute for them under the plan's rules. That does not make the SEP a poor choice. It means the plan should be evaluated as an employee-benefit decision as well as an owner-retirement decision.
If hiring is part of reducing owner dependence, model future plan costs before assuming today's structure will remain ideal. A plan that works for a solo owner may need to evolve when the company builds a team.
The Takeaway
For a business owner with variable income, a SEP IRA can provide useful contribution flexibility. Review cash flow, employee obligations, personal wealth outside the company, and the investments required to make the business less founder-dependent. Then use the 30-day-away test to see whether the company is becoming more transferable over time.
At Seek & Find Financial, we help business owners connect retirement-plan decisions with taxes, liquidity, personal wealth, and business-transition goals so a strong year supports more than one part of the owner's future.
Review the SEP Before Every Major Business Change
Variable income is only one reason to revisit a SEP. Hiring an employee, changing the entity structure, adjusting owner compensation, or moving closer to a sale can change how the plan fits. An annual review should compare the contribution strategy with the company's next twelve
months, not simply repeat the prior year's percentage.
Owners should also keep records organized and confirm that contributions are calculated using the correct compensation rules. A contribution error can turn a useful planning tool into an administrative problem.
The broader objective is consistency of decision-making. Even when the contribution amount changes, the owner should use the same framework each year: protect liquidity, meet plan obligations, build outside wealth, and invest in the parts of the business that make the founder less essential.
Investing involves risk, including possible loss of principal. No investment strategy can ensure financial success or guarantee against losses. Past performance may not be used to predict future results. Provided content is for overview and informational purposes only, reflects the opinions of the author, and is not intended and should not be relied upon as individualized tax, legal, fiduciary, or investment advice.
This information is being provided only as a general source of information. These views may change as market or other conditions change. This information is not intended and should not be used to provide financial advice and does not address or account for an individual’s circumstances. Past performance does not guarantee future results, and no forecast should be considered a guarantee. Please seek the guidance of a financial professional regarding your particular financial concerns.
Investment advisory services offered by duly registered individuals through Seek & find Financial LLC a Registered Investment Adviser. Licensed Insurance Professional.