Why Retirement Plans Are One of the Most Important Financial Decisions You Will Make
If you are unsure how to save for retirement, you are not alone. Many people have access to several account types but still do not know which one to use first, how taxes work, or how to build a plan that fits real life.
Retirement plans are tax-advantaged accounts and structures that help you save and invest for the future. There are many types, and choosing the right one can save you a large amount in taxes over time.
Here is a quick look at the main retirement plan types:
- 401(k): Best for employees at private companies. 2025 contribution limit: $23,500 + catch-up.
- 403(b): Best for nonprofit and school employees. 2025 contribution limit: $23,500 + catch-up.
- 457(b): Best for government employees. 2025 contribution limit: $23,500 + catch-up.
- Traditional IRA: Best for anyone with earned income. 2025 contribution limit: $7,000.
- Roth IRA: Best for those expecting higher future taxes. 2025 contribution limit: $7,000.
- SEP IRA: Best for self-employed people and small business owners. 2025 contribution limit: up to $70,000.
- SIMPLE IRA: Best for small businesses with employees. 2025 contribution limit: $16,500.
- Solo 401(k): Best for self-employed people with no employees. 2025 contribution limit: up to $70,000.
- Defined Benefit Plan: Best for high earners and older business owners. 2025 contribution limit: varies by formula.
Even with more choices than ever, many workers feel behind on retirement savings. At the same time, fewer private-sector workers have traditional pensions. That means most people need to build their own system for saving, investing, and creating future income.
The hard part is not only saving money. It is knowing which accounts to use, when to use them, and how to combine them in a tax-smart way. For business owners and high earners, the wrong setup can mean missed deductions and less flexibility later.
This guide explains the main retirement plan types, 2025 and 2026 contribution limits, tax rules, and how to build a strategy that fits your situation.
I'm Daniel Delaney, Founder of Seek & Find Financial. I have spent my career helping individuals and business owners build clear, practical retirement plans through work at established institutions and now as an independent advisor. In the sections below, I will walk through the key rules and tradeoffs so you can make informed decisions.
Investing involves risk, including possible loss of principal. No investment strategy can ensure financial success or guarantee against losses. Past performance may not be used to predict future results. Provided content is for overview and informational purposes only, reflect the opinions of the author, and is not intended and should not be relied upon as individualized tax, legal, fiduciary, or investment advice.
This information is being provided only as a general source of information. These views may change as market or other conditions change. This information is not intended and should not be used to provide financial advice and does not address or account for an individual’s circumstances. Past performance does not guarantee future results and no forecast should be considered a guarantee. Please seek the guidance of a financial professional regarding your particular financial concerns.
Investment advisory services offered by duly registered individuals through Seek & find Financial LLC a Registered Investment Adviser. Licensed Insurance Professional
The Main Types of Retirement Plans in the US
Most retirement plans fall into a few main groups:
- Workplace plans like 401(k), 403(b), and 457(b)
- IRAs you open yourself
- Small business and self-employed plans like SEP IRAs, SIMPLE IRAs, and solo 401(k)s
- Pensions and cash balance plans
- Insurance-based income tools like annuities
- Executive-only plans like nonqualified deferred compensation
The IRS keeps a broad list of recognized plan types here: Retirement plans | Internal Revenue Service

Defined Benefit vs Defined Contribution Retirement Plans
This is the first split that matters.
A defined benefit plan promises a future benefit. This is often a monthly payment in retirement based on salary, years of service, or a plan formula. Traditional pensions fit here. Cash balance plans do too, even though they may look like account balances.
A defined contribution plan does not promise a monthly payment later. Instead, contributions go into your account, and your future income depends on:
- How much goes in
- How investments perform
- When you take money out
401(k)s, 403(b)s, 457(b)s, IRAs, SEPs, and SIMPLE plans are defined contribution plans.
In simple terms, a pension puts more funding risk on the employer. A 401(k) puts more saving and investment responsibility on you.
Employer-Sponsored Retirement Plans
These are plans tied to your job. Common examples include:
- 401(k) plans for private-sector workers
- 403(b) plans for many school and nonprofit workers
- 457(b) plans for many state and local government workers
- Profit-sharing plans funded by employers
- Money purchase plans with required employer contributions
- ESOPs, which invest mainly in company stock
Individual Retirement Plans
IRAs are accounts you open outside work, though they can also receive rollovers from old employer plans.
Main IRA types include:
- Traditional IRA
- Roth IRA
- Rollover IRA
- Spousal IRA
Small Business and Self-Employed Retirement Plans
If you own a business or work for yourself, you usually have more control and more responsibility. Common choices are:
- SEP IRA
- SIMPLE IRA
- Solo 401(k)
- Cash balance plan
- Traditional defined benefit plan
The IRS has a strong overview here: Retirement plans for self-employed people | Internal Revenue Service
How 401(k), 403(b), and 457(b) Retirement Plans Compare
These three plans look similar at first glance because they all allow salary deferrals and tax-deferred growth. But the rules are not identical.
| Feature | 401(k) | 403(b) | 457(b) |
|---|---|---|---|
| Typical employer | Private company | Public school, church, nonprofit | Government, some tax-exempt employers |
| Employee limit 2025 | $23,500 | $23,500 | $23,500 |
| Employee limit 2026 | $24,500 | $24,500 | $24,500 |
| Roth option | Often available | Often available | Sometimes available |
| Match | Common | Sometimes | Varies |
| Early withdrawal penalty before 59 1/2 | Usually yes | Usually yes | Often no for governmental 457(b) after separation |
401(k) Plans: Who They Are For and How They Work
A 401(k) is the main workplace retirement plan in the private sector. Employees elect to defer part of salary into the plan, usually pre-tax or Roth. Employers may add:
- Matching contributions
- Profit-sharing contributions
- Nonelective contributions
IRS guidance is here: 401(k) plan overview | Internal Revenue Service
There are a few common versions:
- Traditional 401(k)
- Safe harbor 401(k)
- SIMPLE 401(k)
Safe harbor plans require employer contributions that are fully vested right away and can help employers avoid some annual nondiscrimination testing. SIMPLE 401(k)s are for smaller employers and come with their own rules.
403(b) Plans: Nonprofit and School Retirement Plans
403(b) plans are often used by:
- Public schools
- Colleges
- Churches
- Nonprofit organizations
They work a lot like 401(k)s, but the employer type is different. Investment menus may include mutual funds or annuity contracts. Eligibility and match rules depend on the plan sponsor.
457(b) Plans: Government and Special Catch-Up Rules
457(b) plans are common for:
- State employees
- Local government workers
- Some tax-exempt organization employees
Their biggest headline feature is withdrawal flexibility. In many governmental 457(b) plans, distributions after leaving the employer are not hit with the usual 10 percent early withdrawal penalty before age 59 1/2. That can make them more flexible than 401(k)s and 403(b)s for someone retiring early.
2025 and 2026 Contribution Limits for These Retirement Plans
For 2025, the employee deferral limit for 401(k), 403(b), and 457(b) plans is $23,500.
For 2026, that limit rises to $24,500.
Catch-up rules:
- Age 50 and older: additional $7,500
- Ages 60 to 63: higher catch-up may apply under current law, with research noting $11,250 for 2025
Also remember that plans have an annual additions limit and compensation cap. Research notes the compensation cap was $345,000 for 2024 for 401(k) calculations. These limits generally adjust over time, so current-year confirmation matters.
IRA Retirement Plans Explained
IRAs are simple in concept but often confusing in practice.
An IRA can give you:
- A tax deduction now, if it is traditional and you qualify
- Tax-free qualified withdrawals later, if it is Roth
- More investment control than many workplace plans
- A place to roll over old employer plans
For more detail, see our IRA for Business Owners Complete Guide
Traditional IRA vs Roth IRA
A traditional IRA may give you a tax deduction for contributions, depending on income and whether you are covered by a workplace plan. Money grows tax-deferred, and withdrawals are usually taxable later.
A Roth IRA does not usually give you a deduction up front. But qualified withdrawals in retirement are tax-free.
A simple rule of thumb:
- Traditional IRA can make sense if you want tax relief now
- Roth IRA can make sense if you expect higher tax rates later or want tax-free income in retirement
Roth IRA contributions, but not earnings, can generally be withdrawn at any time without tax or penalty. That makes Roth dollars more flexible than many people think.
Related reads:
SEP IRA and SIMPLE IRA for Business Owners
A SEP IRA is funded only by the employer. Employees do not make salary deferrals into a SEP. For 2025, contributions can be up to 25 percent of compensation or $70,000, whichever is less, based on the research provided. Contributions must generally be made uniformly for eligible employees, and they are immediately vested.
IRS SEP guidance: Simplified Employee Pension plan (SEP) | Internal Revenue Service
A SIMPLE IRA is designed for smaller employers. Employees can defer salary, and the employer must generally either:
- Match contributions up to a set percentage, or
- Make a nonelective contribution
The employee contribution limit for 2025 is $16,500 based on the research above.
More on small business planning: Retirement Savings Plans for Small Business Owners
Rollover IRAs and When to Use One
A rollover IRA is often used when you leave a job and move money from an old workplace plan.
A direct rollover is usually the cleanest method because funds move straight from one custodian to another. That helps avoid accidental taxes or withholding issues.
Reasons to use one:
- Consolidate old accounts
- Get broader investment options
- Make the account easier to manage
IRA Contribution Limits and Tax Benefits for 2025 and 2026
For 2025, the IRA contribution limit is $7,000, plus a $1,000 catch-up if age 50 or older.
For 2026, the IRS notes the IRA limit increases to $7,500.
Roth IRA eligibility and traditional IRA deduction rules can phase out at higher incomes, so high earners should confirm income thresholds before assuming full eligibility.
Rules That Matter Most: Matching, Vesting, Withdrawals, and RMDs
The plan type matters. But the fine print often matters more.
How Employer Matching Contributions and Vesting Work
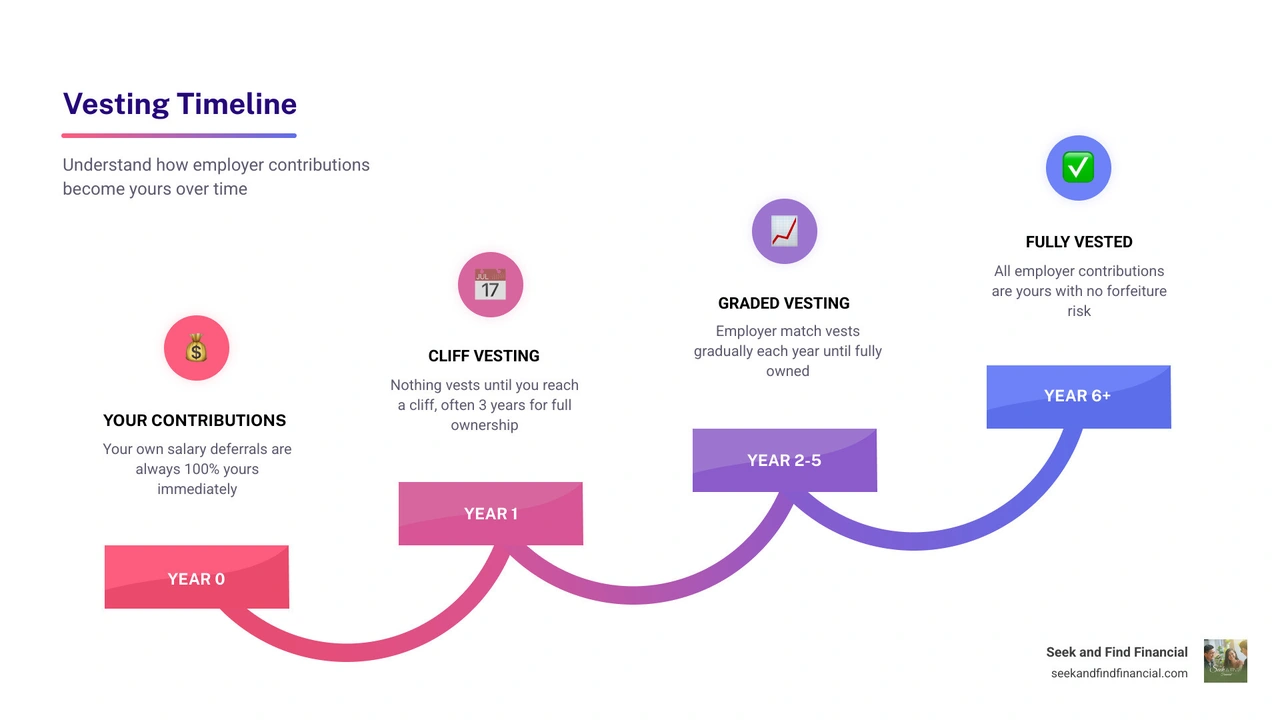
A match means your employer contributes when you contribute. A common formula is something like 100 percent of the first 3 percent of pay, or 50 percent of the first 6 percent.
Important point: your own salary deferrals are always yours. Employer contributions may vest over time.
Common vesting schedules:
- Cliff vesting: 0 percent vested until a set date, then 100 percent
- Graded vesting: ownership builds gradually each year
Exceptions matter:
- Safe harbor 401(k) employer contributions are generally fully vested right away
- SIMPLE 401(k) contributions must be fully vested immediately
- SEP IRA contributions are immediately 100 percent vested
Early Withdrawal Rules and Penalties by Plan Type
In many plans, withdrawals before age 59 1/2 can trigger:
- Ordinary income tax on pre-tax amounts
- A 10 percent early withdrawal penalty
But there are exceptions.
Examples:
- Roth IRA contributions can usually come out tax- and penalty-free
- Governmental 457(b) plans often allow post-separation withdrawals without the 10 percent penalty
- Some plans allow hardship distributions
- Some 401(k) plans allow loans
Just because you can access money does not mean you should. Cashing out retirement accounts early is one of the fastest ways to shrink future wealth.
Required Minimum Distributions in 2026
RMDs generally begin after age 73 under current IRS guidance referenced in the research.
That means most traditional pre-tax retirement accounts eventually force taxable withdrawals, including:
- Traditional IRAs
- Pre-tax 401(k)s
- Pre-tax 403(b)s
- Pre-tax 457(b)s
Roth treatment is different. Roth IRAs generally do not require lifetime RMDs for the original owner. Rules for inherited accounts are separate and can get tricky fast.
Tax Treatment at Contribution and Withdrawal
Here is the simple framework:
- Pre-tax contribution: tax break now, taxable later
- Roth contribution: taxed now, tax-free qualified withdrawals later
- Tax-deferred growth: no annual tax drag inside the account
Choosing between pre-tax and Roth often comes down to one core question: do you expect your tax rate to be higher now or later?
Best Retirement Plans for Self-Employed People, High Earners, and Small Business Owners
Business owners often need retirement plans to do two jobs at once:
- Build long-term wealth
- Create tax deductions now
That is where planning gets strategic.
For entrepreneurs, we also cover this here: Retirement Planning: An Entrepreneur's Guide
Solo 401(k) vs SEP IRA vs SIMPLE IRA
If you are self-employed with no employees, the solo 401(k) is often the most flexible choice.
Why many people like it:
- High total contribution limit
- Employee deferral plus employer contribution structure
- Catch-up contributions if age 50+
- Potential Roth feature, depending on setup
The research notes a solo 401(k) total annual contribution limit of $70,000 for 2025, not counting catch-up contributions.
SEP IRA strengths:
- Very easy to set up
- Low admin burden
- Flexible annual employer contributions
SIMPLE IRA strengths:
- Good for small teams
- Employees can contribute
- Lower admin burden than many 401(k)s
Tradeoff: SIMPLE IRA limits are lower, and employer contributions are generally required.
When a Cash Balance Plan or Defined Benefit Plan Makes Sense
For high earners with strong, steady income, a cash balance or defined benefit plan can allow much larger deductible contributions than a SEP or solo 401(k).
These plans often make the most sense when:
- The owner is older
- Income is high and stable
- The goal is to accelerate retirement savings
- The business can commit to required funding
They are more complex and usually require actuarial work, but the tax deductions can be powerful.
More here: Retirement Plans for High Earners
Nonqualified Deferred Compensation, Annuities, and Pensions
These are not the first plans most people use, but they matter in the right situation.
Nonqualified deferred compensation plans let some executives defer income outside qualified plan limits. They can be useful, but they carry employer-credit risk and fewer protections.
Annuities are insurance contracts that can turn savings into guaranteed income. They may fit people who want predictable income and are willing to trade some flexibility.
Pensions are still valuable where available, but they are much less common than they once were.
How to Choose the Right Retirement Plans for Your Situation
We usually look at these factors first:
- Are you an employee or business owner?
- Do you have employees?
- How much do you want to save?
- Do you want tax savings now or later?
- Is income stable or uneven?
- How old are you, and how far are you from retirement?
For business owners, one wrong choice can cost years of missed deductions. One right choice can create a meaningful tax strategy.
How to Maximize Retirement Plan Savings Over Time
The best retirement plan is not just the one with the highest limit. It is the one you actually use well, year after year.
The IRS also provides employer planning guidance here: Choosing a retirement plan: Plan options | Internal Revenue Service
A Simple Order of Operations for Retirement Savings
A practical savings order often looks like this:
- Contribute enough to get the full employer match
- Fund an IRA if eligible
- Increase workplace plan contributions
- Coordinate with an HSA if eligible
- Save extra in taxable accounts if needed
This order is not universal, but it is a strong starting point.
Strategies to Improve Long-Term Results
A few habits matter more than heroic one-time efforts:
- Automate contributions
- Increase savings rate each year
- Use diversified, low-cost investments
- Keep a mix of pre-tax and Roth assets for tax flexibility
- Rebalance periodically
- Review beneficiaries after life changes
- Avoid loans and cash-outs when possible
Common Mistakes to Avoid With Retirement Plans
Common errors we see:
- Missing the employer match
- Leaving old accounts scattered everywhere
- Cashing out when changing jobs
- Ignoring vesting schedules
- Having the wrong investment mix
- Forgetting beneficiary updates
- Focusing only on contribution limits and not tax strategy
Frequently Asked Questions about Retirement Plans
What are the best retirement plans if I am self-employed with no employees?
Usually the top choices are:
- Solo 401(k)
- SEP IRA
- Cash balance or defined benefit plan for higher-income cases
The solo 401(k) often wins on flexibility and contribution design. SEP IRAs win on simplicity.
Can I contribute to both a 401(k) and an IRA in the same year?
Yes. Many people can contribute to both in the same year.
But there is a catch:
- 401(k) contribution rules are separate from IRA contribution rules
- Traditional IRA deductions can be limited by income
- Roth IRA eligibility can phase out at higher incomes
So "can I contribute?" and "can I deduct it?" are not always the same question.
Which retirement plans have the most flexible withdrawal rules?
In general, the more flexible options include:
- Roth IRA, because contributions can usually be withdrawn anytime
- Governmental 457(b), because the 10 percent penalty often does not apply after separation
- Taxable accounts, though they are not retirement plans
Flexibility is nice. Tax benefits are nice too. The real trick is balancing both.
Conclusion
There is no single best answer for everyone when it comes to retirement plans. The right strategy depends on your job, income, business structure, tax bracket, and long-term goals.
For some people, the best next step is simple: get the 401(k) match and fund an IRA. For others, especially business owners and high earners, a better answer may be a layered strategy using a solo 401(k), SEP IRA, or even a cash balance plan.
What matters most is having a clear structure. Good retirement planning is not about chasing a new idea every year. It is about making steady, tax-aware decisions over time.
If you want to go deeper, here are two helpful next steps:
Investing involves risk, including possible loss of principal. No investment strategy can ensure financial success or guarantee against losses. Past performance may not be used to predict future results. Provided content is for overview and informational purposes only, reflect the opinions of the author, and is not intended and should not be relied upon as individualized tax, legal, fiduciary, or investment advice.
This information is being provided only as a general source of information. These views may change as market or other conditions change. This information is not intended and should not be used to provide financial advice and does not address or account for an individual’s circumstances. Past performance does not guarantee future results and no forecast should be considered a guarantee. Please seek the guidance of a financial professional regarding your particular financial concerns.
Investment advisory services offered by duly registered individuals through Seek & find Financial LLC a Registered Investment Adviser. Licensed Insurance Professional