The Retirement Gap Most Entrepreneurs Don't See Until It's Too Late
Many business owners wake up to the same problem later than they should. They spent years building income but never built a clear retirement system.
An entrepreneur retirement plan is not one account. It is a system. It often includes tax-advantaged accounts, business equity, and a plan for what happens when you stop running the business.
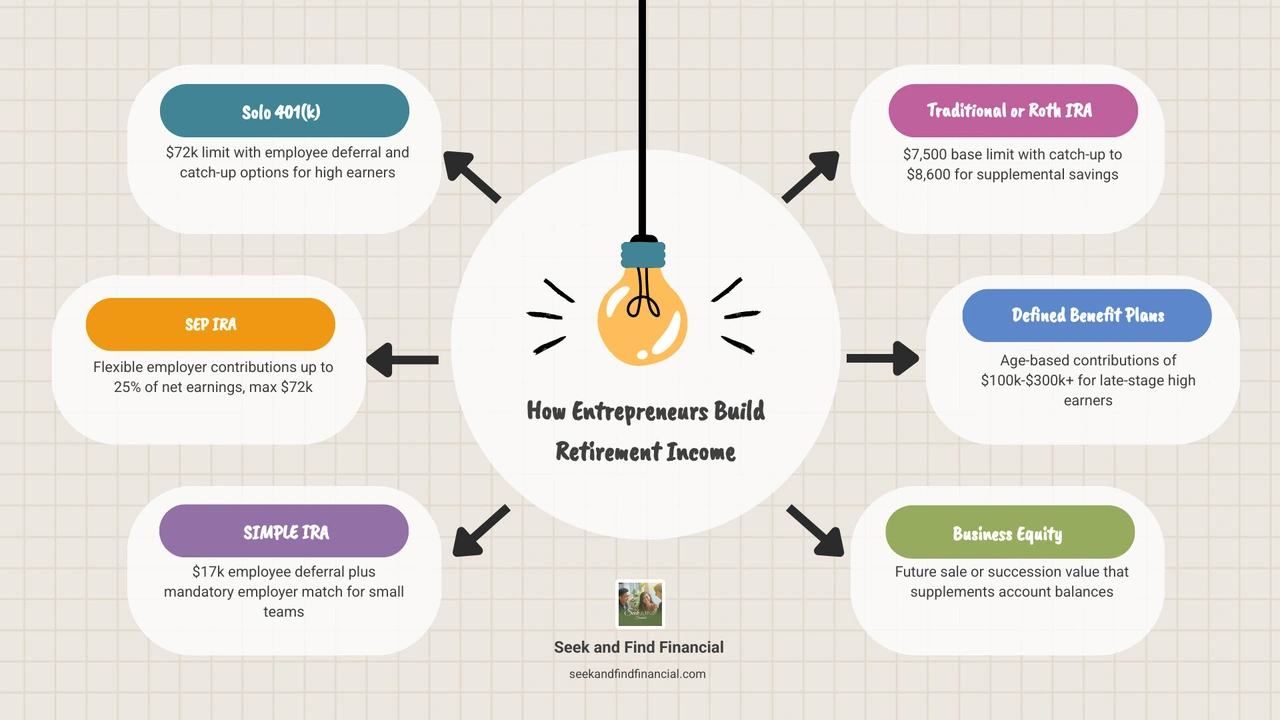
Here is a quick look at the main options available to business owners in 2026:
- Solo 401(k): $72,000 in 2026, or $80,000 if age 50+. Best for solo owners and high earners.
- SEP IRA: Up to $72,000 in 2026, limited to 25% of net earnings. Best for solopreneurs and flexible income years.
- SIMPLE IRA: $17,000 in 2026, or $21,000 if age 50+. Best for small businesses with under 100 employees.
- Traditional or Roth IRA: $7,500 in 2026, or $8,600 if age 50+. Best for supplemental retirement savings.
- Defined Benefit or Cash Balance Plan: Often $100,000 to $300,000+ depending on age and income. Best for $300K+ earners and late savers.
Most employees get a workplace plan handed to them. If you are self-employed, you have to build that system yourself.
That is the gap.
The challenge is not only picking a plan. It is saving when income goes up and down. It is deciding how much of your future depends on the business. It is knowing what happens if you never sell, or if the sale comes later than expected.
Financial advisors often suggest saving 15% to 25% of pretax income each year. Late starters may need 20% to 30%. But for many business owners, the first problem is simpler. They need to know where that money should go.
This guide walks through the main retirement plan options for business owners, how to save when income is uneven, and how your exit plan connects to retirement security.
At Seek & Find Financial, we help business owners think about retirement as part of a bigger wealth plan. That means looking at accounts, taxes, cash flow, and business value together instead of treating them like separate decisions.
Easy Entrepreneur retirement plan word list:
Entrepreneur retirement plan basics: what business owners can actually use
A real Entrepreneur retirement plan usually includes more than one bucket. For many owners, that means a business retirement plan plus an IRA, and sometimes an HSA for future healthcare costs.
Self-employed people can use many of the same tax-deferred tools available in larger companies. The difference is that you are the one setting up the system, funding it, and staying compliant.

Which plans count as an Entrepreneur retirement plan
The main choices are:
- SEP IRA
- Solo 401(k)
- SIMPLE IRA
- Traditional IRA
- Roth IRA
- Defined benefit plan
- Cash balance plan
- HSA, if you have an eligible health plan
Each one solves a different problem.
- SEP IRA is simple and flexible.
- Solo 401(k) often works well for owner-only businesses because it allows both employee deferrals and employer contributions.
- SIMPLE IRA can work for smaller teams with under 100 employees.
- Traditional and Roth IRAs are often good add-ons, not full solutions by themselves.
- Defined benefit and cash balance plans can create very large deductions for high-income owners.
- HSAs can help cover retirement healthcare costs with triple tax advantages when used correctly.
If you want a broader look at plan structures, see our guide to Retirement Savings Plans for Small Business Owners.
Who can use each plan based on business size
Eligibility matters more than most people think.
- Solo 401(k): Best for a business with no employees other than the owner and possibly a spouse.
- SEP IRA: Works for self-employed owners and small businesses, but if you have eligible employees, you generally must contribute the same percentage for them as for yourself.
- SIMPLE IRA: For businesses with 100 or fewer employees and requires employer contributions.
- Traditional or Roth IRA: Available to individuals, though deductibility and Roth eligibility can depend on income.
- Defined benefit or cash balance plan: Best for owners with strong income, stable cash flow, and a willingness to handle more administration.
A key point: one-participant 401(k) plans are generally exempt from discrimination testing when there are no employees other than a spouse. That makes them especially appealing for solo entrepreneurs.
What happened to Keogh plans and why it still matters
You may still hear the term "Keogh plan." That is mostly old language. The IRS no longer treats Keogh plans as a separate modern category in the way people once did. Today, business owners usually choose from SEP IRAs, 401(k)s, SIMPLE IRAs, profit-sharing plans, or defined benefit plans.
Why does this matter? Because some entrepreneurs think there is a secret old-school plan they are missing. Usually there is not. It is just outdated terminology.
Entrepreneur retirement plan comparison: limits, taxes, and setup rules for 2026
Below is the quick comparison most owners want first.

SEP IRA vs Solo 401(k): best fit for high savings years
These are the two plans most solo owners compare.
A SEP IRA is usually easier to open and maintain. It is funded only by the employer side, which means contributions are flexible. If cash flow is tight this year, you can contribute less or even skip a year. SEP plans can also generally be set up by your tax filing deadline, including extensions.
A Solo 401(k) is often more powerful when income is high or when you want to save aggressively. You can contribute both as employee and employer. That can make it easier to reach the maximum at lower income levels than a SEP IRA.
Solo 401(k) plans can also be designed with features like participant loans or hardship rules, depending on plan design. But they bring more paperwork. Once plan assets exceed $250,000, Form 5500-EZ is generally required.
For a deeper comparison, read our IRA for Business Owners Complete Guide.
SIMPLE IRA vs Traditional and Roth IRA: lower limits, easier setup
A SIMPLE IRA can be a useful middle ground for businesses with employees. In 2026, the employee contribution limit is $17,000, with a $4,000 catch-up for those over 50. The tradeoff is that the employer must make required contributions each year.
Traditional and Roth IRAs are much easier to set up, but the limits are much lower. In 2026, the limit is $7,500, plus a $1,000 catch-up if age 50 or older. These accounts are usually best used as supplements to a larger business plan.
The tax difference matters:
- Traditional IRA: may give you a deduction now, but withdrawals are taxed later.
- Roth IRA: no deduction now, but qualified withdrawals are tax-free later.
Roth IRA eligibility can phase out at higher incomes. For married couples filing jointly in 2026, the phaseout range begins at high income levels, so many successful business owners need to check eligibility carefully.
You can learn more in our guides to Traditional IRA for High Income Earners and Roth IRA for High Earners Guide.
Defined benefit and cash balance plans for $300K to $400K+ earners
For high-income entrepreneurs, especially those earning $300,000 to $400,000+, defined benefit and cash balance plans deserve serious attention.
These plans can allow six-figure annual contributions. In many cases, that means far larger deductions than a SEP IRA or Solo 401(k). Age matters here. Older owners can often contribute much more because the funding goal is based on reaching a target retirement benefit in a shorter time frame.
The tradeoff is commitment.
These plans usually require:
- actuarial calculations
- annual administration
- steady funding
- close tax coordination
They are not ideal for every owner. If your cash flow is unpredictable or you may not want to keep funding for several years, the plan can feel hard to keep up with.
But when income is strong and tax pressure is high, they can be one of the most effective tools available. See our Retirement Plans for High Earners.
How to choose the right plan when income is uneven
Entrepreneurs do not get neat, tidy paychecks every two weeks. Some months are feast. Some are ramen. Your plan should respect that reality.
A good starting point is still the standard savings target:
- 15% to 25% of pretax income for many savers
- 20% to 30% for late starters
But the right account depends on:
- employee count
- business structure
- income stability
- age
- tax bracket
- retirement timeline
- whether you need flexibility or maximum deductions
How to save for retirement with irregular business income
This is where many good plans fail in real life. The account may be right, but the funding habit is wrong.
What tends to work better:
- Save by percentage, not by fixed dollar amount.
- Review contributions quarterly.
- Keep a separate savings bucket for taxes and planned retirement contributions.
- Automate a minimum contribution amount even during slow months.
- Use stronger months to catch up.
- Keep an emergency reserve so retirement contributions do not get raided every time revenue dips.
Consistent small savings usually beats waiting for the magical future month when everything is finally "settled down." For most entrepreneurs, that month never arrives.
We cover this mindset more in our Retirement Planning Entrepreneurs Guide.
How your plan should change as the business grows
The right plan at startup may not be the right plan five years later.
- Early stage: IRAs, SEP IRAs, or Solo 401(k)s are often enough.
- First hires: employee eligibility rules become a big deal.
- Growing team: SEP IRAs can get expensive because equal percentage contributions may be required for employees.
- Mature business: SIMPLE IRA, 401(k), pooled arrangements, or defined benefit strategies may become more attractive.
- Pre-retirement stage: large deduction plans and exit planning move to the front of the line.
This is also where compensation design matters. S corporation wages, owner draws, and timing of contributions can all affect how much you can save.
For more on this, see our Business Owner Financial Planning Guide.
How Entrepreneur retirement plan choices affect taxes and take-home pay
Every plan changes your tax picture a little differently.
- Pre-tax contributions can reduce current taxable income.
- Roth contributions do not lower taxes now, but they can create tax-free income later.
- SEP and employer contributions may lower taxable income, but not always self-employment taxes in the same way owners expect.
- S corporation owners often need careful wage planning because retirement contribution formulas may depend on W-2 compensation.
Timing matters too. Some plans must be set up by certain dates. Others can be funded later. That can create planning opportunities, but only if you look ahead before year-end.
More on that in our Financial Advice for Entrepreneurs.
Using retirement money to fund a business: ROBS, risks, and better questions to ask first
ROBS stands for Rollovers for Business Startups. It is a structure that allows certain retirement funds to be rolled into a new company retirement plan, which then buys stock in a new C corporation. That means you may access retirement money for business funding without an early withdrawal penalty or immediate tax bill.
A basic overview of the process is available here: ROBS FAQ.
When ROBS can work and why some owners consider it
Some owners like ROBS because it can provide:
- startup capital without loan payments
- no early withdrawal penalty if done correctly
- no credit underwriting
- funding for an active business you will actually run
It is often considered for buying a business, launching a franchise, or creating a debt-free start.
The real downsides of using retirement funds for your business
This is where the glossy brochure usually gets quiet.
ROBS can create major concentration risk. You are taking retirement money that could be invested across many assets and putting it into one private business, your own. If the business struggles, both your income and your retirement capital can get hit at the same time.
Other issues include:
- the business must be a C corporation
- the plan must generally be offered to eligible employees
- there are ongoing IRS and Department of Labor compliance requirements
- annual filings are required
- prohibited transaction mistakes can be costly
- you may lose years of market compounding if the business underperforms
In plain English, ROBS is not free money. It is swapping diversified retirement capital for concentrated business risk.
Smarter ways to compare ROBS with other retirement strategies
Before using retirement money to fund a business, we think owners should ask:
- Could an SBA loan preserve retirement assets better?
- Should we use only part of retirement funds instead of all of them?
- Do we already have enough assets outside the business?
- What happens if the business does not work?
- How does the tax model compare over five to ten years?
ROBS can be valid in the right case. But it should be modeled carefully, not chosen because it sounds easier than a loan.
Exit planning is part of retirement planning
A lot of entrepreneurs assume the business will pay for retirement. Sometimes it will. Sometimes it will not. That is why exit planning should sit inside retirement planning, not off to the side.
This idea is explored well in Funding Your Exit Without Selling Equity MYCPE ONE Insights.
Why your business should not be your only retirement asset
Your business may be one of your biggest assets. It should not be your only one.
Why?
- concentration risk
- sale timing risk
- valuation risk
- buyer risk
- health risk
- burnout risk
If retirement depends on a perfect sale at a perfect price in a perfect year, that is not a plan. It is a guess.
Building wealth outside the business matters. That can include retirement accounts, taxable investments, and sometimes an HSA for future healthcare costs.
How business valuation and succession shape retirement income
Your business value affects how much retirement income you may have later. But value is not only revenue. Buyers and successors often look for:
- clean financials
- repeatable profit
- low owner dependence
- documented processes
- strong management depth
- transfer readiness
A family succession plan is different from an internal sale. An internal sale is different from a third-party sale. Each path can change timing, taxes, and how much cash you may actually receive.
If you want to understand this side of the puzzle, our related content on founder exits can help:
When to get professional tax and financial advice
Some choices are simple enough to do on your own. Others are not.
It often makes sense to get professional help when:
- you are choosing between SEP and Solo 401(k)
- you have employees and need to follow plan rules correctly
- you are considering a defined benefit or cash balance plan
- income is high enough that taxes are becoming the main issue
- you are weighing Roth versus pre-tax contributions
- you are preparing for a sale, succession, or retirement transition
This is where coordinated planning matters. Retirement planning, tax strategy, compensation design, and exit planning should work together. That is the difference between having a few accounts and having a real strategy.
For a broader view, see our article on Entrepreneur Wealth Management.
Frequently Asked Questions about Entrepreneur retirement plan choices
Can I contribute to both an IRA and a small business retirement plan?
Yes, often you can. Many entrepreneurs contribute to both an IRA and a SEP IRA or Solo 401(k). The main caution is that IRA deductibility and Roth eligibility may depend on income. The account limits are separate, but the tax rules can overlap.
What is usually the best retirement plan for a solo entrepreneur?
For many solo owners, the Solo 401(k) is the strongest all-around option because of high contribution potential and the ability to contribute as both employee and employer. A SEP IRA can still be great if you want simplicity and contribution flexibility. For very high earners, especially older owners, a defined benefit or cash balance plan may create much larger tax savings.
When does it make sense to switch plans?
Usually when one of these changes happens:
- you hire employees
- your income rises sharply
- you turn 50 and want catch-up contributions
- your tax bill becomes painful
- your retirement window gets shorter
- your business is moving from growth mode to exit mode
Conclusion
A strong Entrepreneur retirement plan is not about finding the fanciest account. It is about matching the right plan to your income, your business size, your tax picture, and your long-term exit path.
For some owners, that means starting with a simple IRA or SEP. For others, it means using a Solo 401(k) to save more in strong income years. And for high earners getting closer to retirement, it may mean adding a defined benefit or cash balance plan to catch up faster.
What matters most is structure.
Save steadily, even when income is uneven. Build wealth outside the business. Treat tax strategy and exit planning as part of retirement planning, not as separate jobs for later. Review the plan as your business changes.
Having a clear, personalized strategy makes a real difference. The right structure turns scattered decisions into a system that works over time.
If you want a clearer framework for that process, here is what we do.
Investing involves risk, including possible loss of principal. No investment strategy can ensure financial success or guarantee against losses. Past performance may not be used to predict future results. Provided content is for overview and informational purposes only, reflect the opinions of the author, and is not intended and should not be relied upon as individualized tax, legal, fiduciary, or investment advice.
This information is being provided only as a general source of information. These views may change as market or other conditions change. This information is not intended and should not be used to provide financial advice and does not address or account for an individual's circumstances. Past performance does not guarantee future results and no forecast should be considered a guarantee. Please seek the guidance of a financial professional regarding your particular financial concerns.
Investment advisory services offered by duly registered individuals through Seek & find Financial LLC a Registered Investment Adviser. Licensed Insurance Professional