Cash Balance Plans for High-Income Business Owners
Learn how cash balance plans fit high-income owner retirement savings, tax planning, employee costs, cash flow, and business transition goals. Card Description: Cash balance plans can accelerate retirement savings, but the business needs stable cash flow and a strategy beyond the tax deduction.
High-income business owners can reach a point where a standard retirement plan does not move enough money outside the company to match their retirement timeline. A cash balance plan may create an additional opportunity for significant tax-deferred retirement funding when the business and owner are a good fit.
The attraction is obvious: larger potential contributions and another way to convert business earnings into personal retirement assets. The commitment is just as important. Cash balance plans require professional administration, actuarial work, and a funding strategy the business can support.
Chapter 3 of Walking to Destiny, “Every Hero Has a Flaw,” provides the right context. The owner should not build a sophisticated retirement plan while ignoring a company that still cannot function without them.
How a Cash Balance Plan Works
A cash balance plan is a type of defined benefit plan. Participants typically see a hypothetical account balance that grows through plan-defined credits, while the employer is responsible for funding the promised benefit under actuarial requirements.
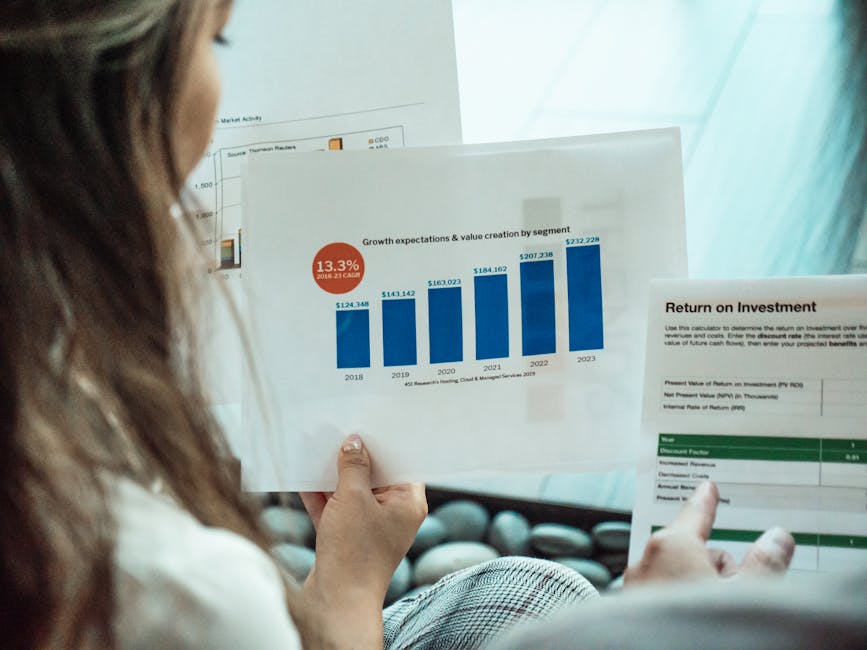
Financial analysis representing the funding commitments involved in a cash balance plan.
For a high-income owner, a cash balance plan can sometimes be paired with a 401(k) and profit-sharing arrangement. The exact design depends on age, compensation, employees, existing plans, and the business's ability to make required contributions.
Stable Cash Flow Matters
A cash balance plan is not simply a contribution that can be turned on and off casually. Before adopting a plan, stress-test company cash flow. What happens if revenue declines? What if a large client leaves? What if the business needs to hire a senior manager?
A tax deduction is useful, but the business still needs enough liquidity to operate and fund improvements that reduce owner dependence.
The 30-Day-Away Test Belongs in the Design Conversation
Imagine the owner is unavailable for 30 days. If revenue, sales, or key decisions stop, the business may still have a transferability problem.
A cash balance plan can help the owner accumulate substantial assets outside the company. But the company also needs leadership, systems, and customer relationships that do not disappear when the founder leaves. For an owner nearing retirement, both projects may need to happen at the same time.
Employees Affect the Economics
Cash balance plans are subject to qualified-plan rules and often cover employees as part of a broader design. Employee demographics can materially affect the economics.
That is why an owner should not rely on a headline contribution estimate. A qualified plan professional and actuary need to model the actual workforce.
Think Beyond the Tax Deduction
The strongest planning question is what the owner wants the plan to accomplish. Is the goal to catch up retirement savings after years of reinvesting in the business? Build more assets outside the company before an exit? Create a benefit program for key employees? Reduce dependence on a future sale?
Those objectives lead to a better design discussion than simply asking for the largest possible deductible contribution.
Coordinate With the Exit Timeline
If the owner expects to sell, merge, or reduce involvement, the retirement-plan team should understand that timeline. Plan termination, successor ownership, employee obligations, and funding should not become surprises during a transaction.
The owner also needs a personal plan that does not assume the business will sell at exactly the right moment. Building retirement assets outside the company can create negotiating flexibility.
The Takeaway
Cash balance plans can be powerful, but they involve actuarial design, funding commitments, employee considerations, and a need for consistent cash flow.
Evaluate the plan alongside the Chapter 3 questions. Can the business operate for 30 days without the founder? Is personal wealth becoming less concentrated in the company? Is enough capital being retained to build leadership and systems?
At Seek & Find Financial, we help business owners evaluate advanced retirement strategies within the larger picture of taxes, liquidity, personal wealth, employee benefits, and business-transition planning.
Stress-Test the Plan Before Committing
Before establishing a cash balance plan, model more than the best-case year. Ask what funding looks like if revenue declines, investment performance differs from assumptions, or the company needs cash for an unexpected business opportunity.
The owner should also understand the administrative calendar. Actuarial calculations, plan documents, tax filings, and coordination with an existing 401(k) require ongoing attention. The value of the strategy depends on operating the plan correctly over time.
A stress test can also include the owner's transition timeline. If retirement is five years away, the business and personal plan should show what needs to happen in each of those years. That makes the cash balance plan part of a defined path toward financial independence rather than an isolated tax tactic.
────────────────────────────────────────
Investing involves risk, including possible loss of principal. No investment strategy can ensure financial success or guarantee against losses. Past performance may not be used to predict future results. Provided content is for overview and informational purposes only, reflect the opinions of the author, and is not intended and should not be relied upon as individualized tax, legal, fiduciary, or investment advice.
This information is being provided only as a general source of information. These views may change as market or other conditions change. This information is not intended and should not be used to provide financial advice and does not address or account for an individual’s circumstances. Past performance does not guarantee future results and no forecast should be considered a guarantee. Please seek the guidance of a financial professional regarding your particular financial concerns.
Investment advisory services offered by duly registered individuals through Seek & find Financial LLC a Registered Investment Adviser. Licensed Insurance Professional.