What Every Business Owner Needs to Know About Exit Planning
A business owner exit strategy is the plan you put in place to transfer or sell your company — on your terms, at the right time, and for the most money possible.
Here is a quick overview of your main options:
- Strategic Acquisition: Typically takes 9-14 months, often values the business at 6x-12x EBITDA, and usually leaves the owner with low control after exit.
- Private Equity Sale: Typically takes 6-12 months, often values the business at 4x-8x EBITDA, and may allow partial control or rollover equity after exit.
- Management Buyout: Typically takes 4-7 months, often values the business at 3x-5x EBITDA, and usually leaves the owner with low control after exit.
- ESOP: Typically takes 6-12 months, often reaches 85-95% of market value, and can offer flexible control during the transition.
- Family Succession: Timing varies, valuation is negotiated, and control after exit depends on the family transfer structure.
- IPO: Typically takes 12-24+ months, offers the highest potential valuation, and usually leaves the owner with low control after exit.
- Liquidation: Typically takes 1-6 months, usually produces the lowest valuation, and leaves the owner with no control after exit.
Most business owners know they will exit someday. The problem? Very few actually plan for it.
According to recent surveys, two-thirds of business owners have no documented exit plan. And 41% have never completed any kind of valuation analysis. That means the majority of founders are building something valuable — without a clear strategy for what happens when it is time to step away.
The result is often an exit that happens on someone else's terms, not their own. A health scare. A partner dispute. An unsolicited offer. Owners who are caught off guard tend to receive 60-75% of what a well-prepared seller would walk away with.
The good news: a structured exit plan changes everything. Owners who start planning 3-5 years before their target exit date consistently sell for 20-40% more than those who react to circumstances. That is not a small difference. On a $5 million business, that gap is $1 million to $2 million — after years of hard work building something real.
This guide walks you through every stage of the process — from choosing the right exit path, to valuing your business, to minimizing taxes and protecting your team.
I'm Daniel Delaney, Founder of Seek & Find Financial, and throughout my career in financial services — including roles at established wealth management firms — I've worked closely with business owners navigating the financial complexity of a business owner exit strategy. That experience shapes the practical, clear-eyed perspective you'll find throughout this guide.
Investing involves risk, including possible loss of principal. No investment strategy can ensure financial success or guarantee against losses. Past performance may not be used to predict future results. Provided content is for overview and informational purposes only, reflect the opinions of the author, and is not intended and should not be relied upon as individualized tax, legal, fiduciary, or investment advice.
This information is being provided only as a general source of information. These views may change as market or other conditions change. This information is not intended and should not be used to provide financial advice and does not address or account for an individual's circumstances. Past performance does not guarantee future results and no forecast should be considered a guarantee. Please seek the guidance of a financial professional regarding your particular financial concerns.
Investment advisory services offered by duly registered individuals through Seek & Find Financial LLC a Registered Investment Adviser. Licensed Insurance Professional.
Business owner exit strategy vocab explained:
Why Every Founder Needs a Business Owner Exit Strategy
Building a business takes years of hard work. Many business owners in places like Valparaiso, Crown Point, and Chicago focus all their energy on daily operations. They forget to plan for the day they will leave. Skipping this step is a big risk.
Many owners face emotional roadblocks. Your business is a major part of your identity. Letting go is hard. It can feel like you are leaving a piece of yourself behind. Some owners do not know where to start. Others do not want to think about life after the business. This emotional attachment often causes owners to delay planning.
There are also financial roadblocks. Many founders have most of their wealth tied up in the company. They do not know how much money they actually need to retire. They do not know what their business is worth. Without a clear financial plan, they risk running out of money after they exit.
Early preparation is the key to success. You should start planning your exit three to five years before you want to step away. This runway gives you time to fix operational weaknesses. It allows you to build a strong management team. It also gives you time to implement tax-saving strategies.
When you plan ahead, you turn your business into a transferable asset. A business that depends entirely on its owner is very hard to sell. If you cannot take a 30-day vacation without your business falling apart, buyers will see your company as highly risky. Early planning helps you build systems so the business runs smoothly without you. This process is a core part of long-term business planning.
To get a complete view of the steps involved, you can read the US Chamber of Commerce guide on exit planning. Writing down your goals is the first step toward a successful transition.
The Seven Primary Exit Paths for Business Owners
Every business owner has different goals. Some want the highest possible price. Others care more about protecting their employees or keeping the business in the family. There are seven primary exit paths to consider.
1. Strategic Acquisitions
A strategic buyer is usually a larger company in your industry. They buy your business because it fits their long-term growth plans. They might want your technology, your customer list, or your geographic reach. Strategic acquisitions usually offer the highest purchase price. This is because the buyer expects to make more money by combining your company with theirs. However, you will have very little control after the sale. The buyer may change your brand, close offices, or lay off staff.
2. Private Equity Sales
Private equity firms are financial buyers. They buy companies to grow them and sell them later for a profit. They often look for healthy companies with strong management teams. In a private equity sale, you might do a partial exit. This means you sell a majority of the business but keep a small ownership stake. This allows you to benefit from a second sale down the road. Private equity deals can be fast, but they focus heavily on financial performance.
3. Management Buyouts (MBO)
In a management buyout, your key employees buy the company from you. This is a great path if you want to preserve your company culture. It also ensures operational continuity. Your employees already know how to run the business. The downside is that employees rarely have enough cash to buy the business outright. You will likely need to carry a seller note. This means you get paid over time, which adds financial risk for you.
4. Employee Stock Ownership Plans (ESOP)
An ESOP is a qualified retirement plan that buys the company on behalf of the employees. It allows you to transition ownership gradually. ESOPs offer massive tax benefits. If you sell at least 30% of your company to an ESOP, you may be able to defer your capital gains taxes. ESOPs are excellent for protecting your legacy and your team. However, they are complex and expensive to set up. They generally work best for companies with stable cash flow and at least 20 employees.
5. Family Succession
Passing the business to a family member is a traditional path. It keeps your legacy alive. However, family transfers fail more than any other exit path. Only about 30% of family businesses survive into the second generation. The main reason is a lack of preparation. Owners often transition ownership without ensuring the next generation is competent or interested. Mixing family dynamics with business decisions can lead to conflict.
6. Initial Public Offerings (IPO)
An IPO is when you sell shares of your company to the public. It is often seen as the ultimate goal for high-growth startups. It can bring a massive payout and great prestige. However, IPOs are rare for small and lower-middle-market businesses. They are highly complex, expensive, and require a valuation of at least $250 million to be viable.
7. Liquidation
Liquidation means closing the business and selling off its assets. This is the simplest and fastest way to exit. However, it usually yields the lowest financial return. You only get paid for the physical assets, like equipment and real estate. Your brand, customer relationships, and goodwill are lost. This path is usually chosen when the business is struggling or when there are no buyers.
To help you compare these options, read Shopify's guide on exit strategy planning. It offers deep insights into choosing the right path for your specific business model. You can also review our guide on the exit strategy for founders to see how early decisions shape your eventual payout.
How to Value Your Business and Avoid Emotional Bias
Many business owners believe their company is worth more than the market will pay. This emotional bias is natural. You have poured years of sweat and tears into the business. But buyers do not pay for your past sacrifices. They pay for future cash flows and risk reduction.
To avoid emotional bias, you need a professional valuation. This process looks at hard numbers rather than personal feelings.
Valuation is typically based on a multiple of your earnings. Two common metrics are:
- EBITDA: Earnings Before Interest, Taxes, Depreciation, and Amortization. This is used for larger, mid-market businesses.
- SDE: Seller's Discretionary Earnings. This is used for smaller, owner-operated businesses. It adds back your personal salary and perks to show the true cash flow of the business.
Buyers apply a multiple to these earnings based on your industry and risk profile. For example, a service business might sell for 3x to 5x EBITDA. A high-growth software company with recurring revenue might sell for 8x to 12x EBITDA.
Several key value drivers can increase your multiple:
- Low Customer Concentration: If your largest customer represents more than 15% of your revenue, your business is risky. If that customer leaves, your business collapses. Diversifying your customer base increases your value.
- Management Depth: A business that can run without you is worth much more. You must build a strong second-tier leadership team.
- Clean Financials: Messy books destroy buyer trust. You should have reviewed or audited financial statements. A sell-side Quality of Earnings (QofE) report is highly recommended. This is a third-party audit that verifies your adjusted EBITDA. It reduces the risk of a buyer trying to lower the price during due diligence.
Focusing on these drivers is a critical part of preparing your business for sale. It ensures you get the highest possible offer when you go to market.
Tax Strategies to Maximize Your After-Tax Proceeds
It is not about what you sell the business for. It is about what you keep after taxes. Tax planning can make a massive difference in your net proceeds.
Asset Sale vs. Stock Sale
The structure of your deal has major tax implications. In an asset sale, the buyer only purchases specific assets, like equipment, inventory, or customer lists. Buyers prefer asset sales because they can step up the basis of the assets and write them off faster. However, asset sales often trigger ordinary income tax rates for the seller, which are much higher than capital gains rates.
In a stock sale, the buyer purchases your entire corporate entity. Sellers prefer stock sales because the entire transaction is typically taxed at long-term capital gains rates. This can save you 15% to 20% in taxes compared to an asset sale.
Section 1202 Qualified Small Business Stock (QSBS)
This is one of the most powerful tax savings tools available. Under IRC Section 1202, if your business qualifies as a Qualified Small Business, you may be able to exclude up to 100% of your capital gains from federal taxes, up to $10 million or 10 times your basis. To qualify, your company must be a domestic C-corporation, have under $50 million in gross assets when the stock was issued, and meet specific active business requirements.
Section 1042 ESOP Rollover
If you sell your C-corporation stock to an ESOP, you can defer your capital gains taxes indefinitely under IRC Section 1042. To do this, the ESOP must own at least 30% of the company after the sale, and you must reinvest the proceeds into "qualified replacement property," such as US corporate stocks or bonds, within a 15-month window.
Installment Sales
An installment sale allows you to receive payments over several years. Under IRC Section 453, you only pay taxes on the gain as you receive the payments. This can keep you in a lower tax bracket and defer your overall tax liability. However, it also means you are taking on buyer default risk.
Integrating these tax tools with your estate plan is essential. We help our clients in Indiana and Illinois coordinate these moves with asset protection strategies to secure their family wealth for generations.
Building Your Transition Team and Timeline
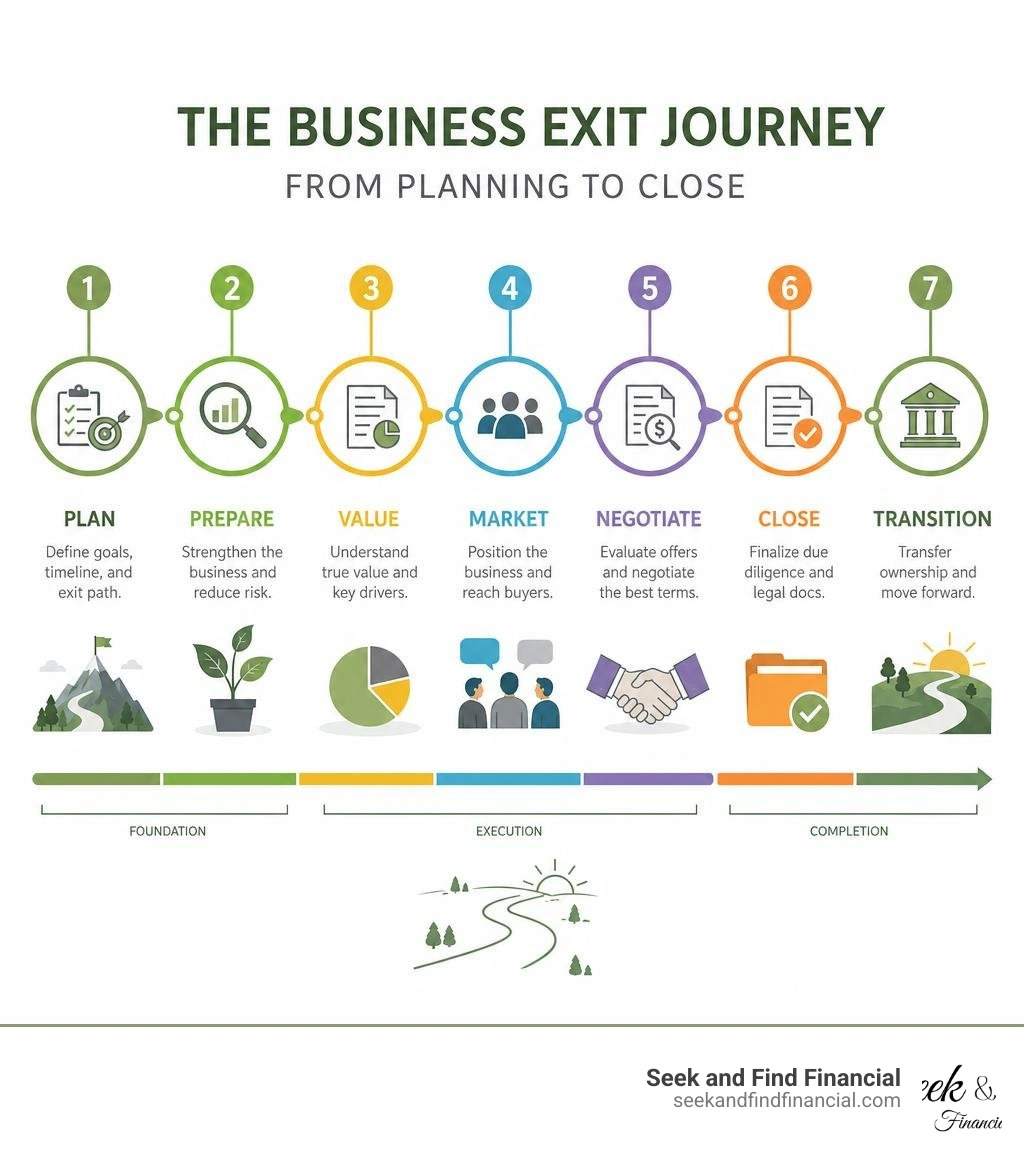
A successful exit is not a single event. It is a structured process that takes time. We recommend using a 24-month transition framework to ensure everything goes smoothly.
The 24-Month Exit Framework
- Months 1-12 (Preparation Phase): This is when you clean up your books, build your management team, and address customer concentration. You should hire a fractional CFO to move to monthly closes. You should also set up your tax and estate planning structures.
- Months 13-18 (Marketing Phase): Your advisory team prepares marketing materials, like a Confidential Information Memorandum (CIM). They reach out to potential buyers and negotiate Letters of Intent (LOIs).
- Months 19-24 (Closing Phase): The buyer conducts deep due diligence. You negotiate the definitive purchase agreement and prepare your team for the transition.
Your Advisory Team
You cannot do this alone. You need a team of specialists who understand the complexities of business transitions:
- M&A Advisor or Investment Banker: They help you find buyers, run a competitive sale process, and negotiate the best deal terms.
- Certified Public Accountant (CPA): They handle tax modeling, prepare your financial statements, and help with the Quality of Earnings report.
- Transaction Attorney: They draft legal documents, manage liability, and ensure the deal structure protects your interests.
- Wealth Manager: We help you determine "your number." This is the net amount you need from the sale to support your lifestyle in retirement. We help you invest the proceeds wisely so you do not run out of money.
Working with a skilled business transition advisor ensures that your personal, business, and financial goals are fully aligned.
Frequently Asked Questions About Business Owner Exit Strategy
When should I start planning my business owner exit strategy?
You should start planning three to five years before your target exit date. This timeline gives you enough runway to increase your business value, build a strong management team, and implement tax-saving strategies. Starting too late often forces you to accept a lower valuation.
What is the most tax-efficient business owner exit strategy?
The most tax-efficient strategy depends on your business structure. For C-corporations, utilizing Section 1202 (QSBS) can allow you to pay zero federal capital gains tax. For business owners selling to their employees, a Section 1042 ESOP rollover offers incredible tax deferral benefits. A stock sale is generally more tax-efficient for sellers than an asset sale.
How do I protect my employees during a business transition?
You can protect your team by using key employee retention agreements. These agreements offer financial bonuses to critical staff who stay with the company through the transition. It is also vital to sequence your communications carefully. Do not inform general staff about a sale until the deal is officially signed and closed to avoid panic and attrition.
Conclusion
Crafting a business owner exit strategy is one of the most important financial projects of your life. It is the bridge that turns your decades of hard work into lasting personal wealth.
At Seek & Find Financial, we specialize in helping business owners earning $400K+ navigate this exact journey. We do not offer generic, cookie-cutter advice. Instead, we use advanced planning tools, like Altruist, to build personalized, technology-driven strategies that fit your real-life goals. Whether you are located in Valparaiso, Crown Point, Chesterton, or Chicago, we are here to help you secure your legacy and build long-term wealth.
If you are ready to start planning your transition, explore our personalized wealth management services today.
Investing involves risk, including possible loss of principal. No investment strategy can ensure financial success or guarantee against losses. Past performance may not be used to predict future results. Provided content is for overview and informational purposes only, reflect the opinions of the author, and is not intended and should not be relied upon as individualized tax, legal, fiduciary, or investment advice.
This information is being provided only as a general source of information. These views may change as market or other conditions change. This information is not intended and should not be used to provide financial advice and does not address or account for an individual’s circumstances. Past performance does not guarantee future results and no forecast should be considered a guarantee. Please seek the guidance of a financial professional regarding your particular financial concerns.
Investment advisory services offered by duly registered individuals through Seek & find Financial LLC a Registered Investment Adviser. Licensed Insurance Professional.